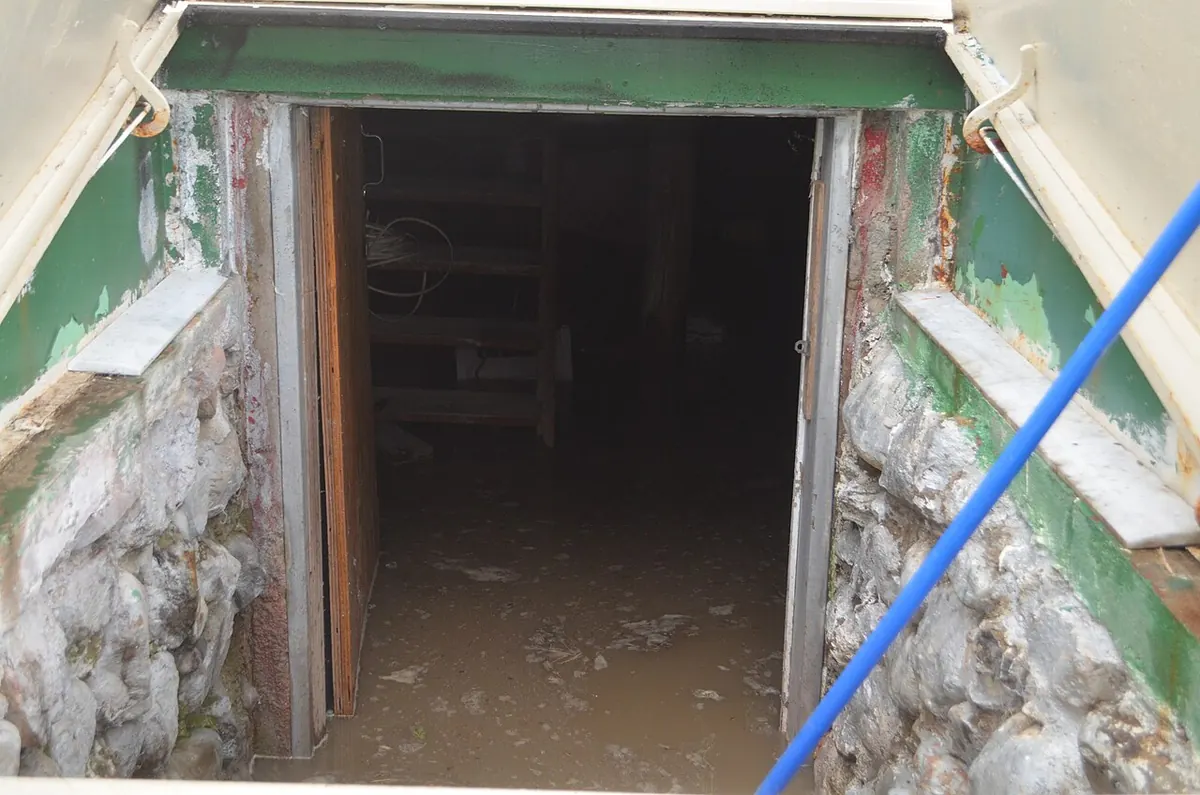
Why this tool exists
When combined sewers surcharge in a heavy rain, water comes up through floor drains in basements across Cook, DuPage and the older suburbs. Most homeowners policies cover that only through a water backup endorsement, and many endorsements carry limits of $5,000 to $25,000 — far less than a finished basement costs to rebuild.
How the estimate works
The tool adds your rebuild, drying, contents and equipment figures, subtracts the deductible and caps the payment at the endorsement limit. Some endorsements apply the deductible differently, and some losses may also fall partly under other coverages, so treat the result as illustrative.
What appraisal can and can’t do
Appraisal can’t raise an endorsement limit. It can settle a dispute about how much a covered loss costs — useful when the carrier underprices the rebuild, or when part of the loss falls under another coverage such as a burst pipe. Read more in our guide to basement backup versus flood.
Questions about this tool
Is a flooded basement from outside water covered by this endorsement?
Usually not. Surface water entering from outside is typically flood, which needs flood insurance. Backup endorsements cover water backing up through drains or sewers.
When should I raise my limit?
Review it at renewal, especially if you’ve finished the basement. Ask your agent to price higher limits.