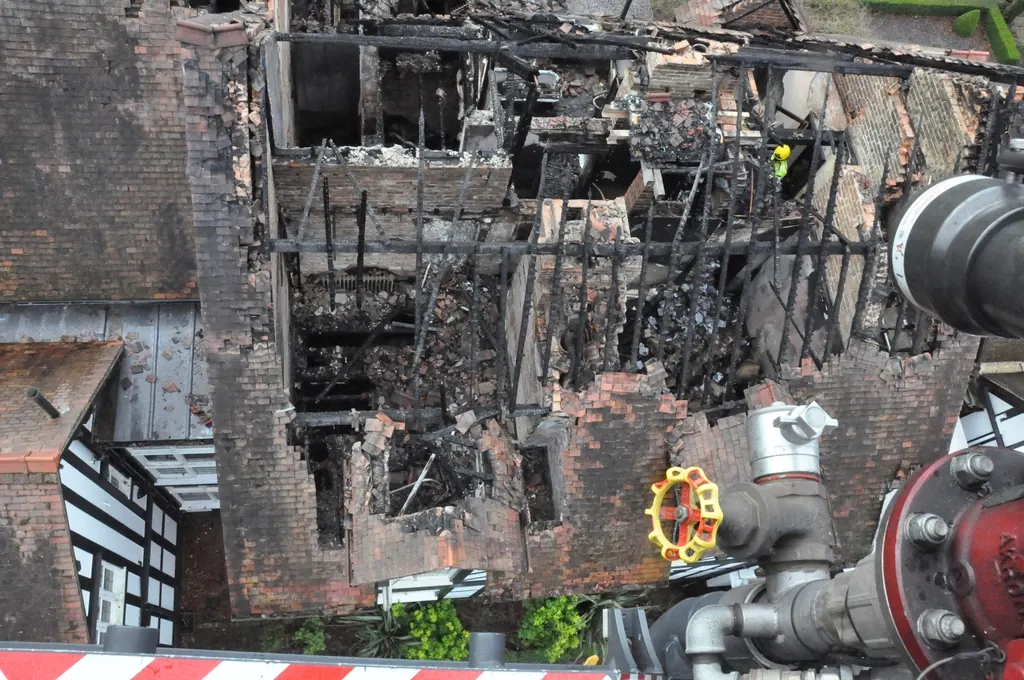
The burn is only the beginning
A kitchen fire contained to one room can still send smoke through the HVAC system, behind outlet covers and into insulation throughout the house. Firefighting water soaks floors and ceilings below. Older Chicago two-flats and balloon-framed houses downstate let smoke travel through open wall cavities from basement to attic. The carrier’s first estimate often covers the fire room well and the rest of the house barely at all.
What we evaluate
- Char depth and structural framing that must be replaced versus sealed.
- Smoke migration testing and the realistic limits of cleaning painted, porous and textured surfaces.
- HVAC cleaning or replacement, including ductwork in walls and ceilings.
- Electrical and code upgrades required when walls are opened.
- Contents: what can be cleaned, what must be replaced, and the age and value of each item.
Additional living expense
Fire losses often involve months out of the home. Additional living expense (loss of use) isn’t always part of the appraisal question, but rebuild timelines drive it. A realistic repair schedule in our estimate supports the time you’ll actually be displaced.
Lightning and grass fires
Downstate, lightning strikes and field fires reach barns, machine sheds and farmhouses. Farm structures may be insured under farm policies with their own valuation rules. We read those forms carefully before we price anything.
Frequently asked questions
The carrier wants to clean, but the smell won’t go away. What can we do?
Document the odor and any failed cleaning attempts. Cleaning versus replacement is a common appraisal question, and testing results can help the panel decide.
Is my contents list part of appraisal?
It can be, if contents values are disputed and the policy’s appraisal clause covers the whole claim. See our contents appraisal service.